Retirement Planning for Marathon Petroleum Employees — Robinson, Illinois
The pension election. The Thrift Plan. The 31-day healthcare window. These are decisions you make once, and you live with them for the rest of your retirement. This is the part of the practice built for the people who make them at Robinson.
ON THIS PAGE
This page is for you if…
If none of those describe you, we still may be able to help — but this particular page probably isn’t the right starting point.
The decisions this practice is built around
Six of them, specifically. They interact with each other, which is why taking them one at a time can be where most of the damage gets done.
01
Your pension election
Single life, or a joint-and-survivor option at 50, 75 or 100 percent. Monthly payments, or a lump sum rolled to an IRA. The right answer depends on your health, your spouse’s age, your other assets and what interest rates are doing the month you elect. It is not a preference question, and once the paperwork is signed it does not get revisited.
02
The Thrift Plan
Leave it, roll it, or begin taking distributions. Each has consequences for taxes, for creditor protection, for investment cost and for access. If your Thrift Plan holds employer stock, there is a separate tax question that gets decided the moment you move the money — and not before.
03
Retiree healthcare, and the 31-day window
You have 31 days after you separate from service to elect retiree health, dental and vision coverage. The window is firm and the election is irrevocable. Separately, the healthcare subsidy you have earned accrues by year of service after age 30 — retiring before you have reached the full percentage is a permanent reduction, not a temporary one.
04
Age 55, and the order of operations
There is a provision that can allow penalty-free distributions from a workplace plan if you separate in the calendar year you turn 55. Rolling that money to an IRA on your last day of work can take the provision off the table. The sequence matters more than the decision.
05
The bridge to Medicare, and what happens at 65
Between your retirement date and your 65th birthday you are covering yourself. At 65 the transition to Medicare runs through Via Benefits and the arithmetic changes again — including income-related surcharges that are calculated on a tax return you filed two years earlier.
06
The first decade of retirement, taxwise
The years between retirement and the start of required distributions are usually the lowest-tax years of an entire adult life. What you do in that window — Roth conversions, bracket management, how you sequence withdrawals — compounds for the next thirty years. Most of it has to be decided before it can be done.
Plan details are described in general terms. Marathon Petroleum may amend or change its plans at any time. Always confirm your own numbers and eligibility with the MPC Benefits Service Center and your Summary Plan Description. Neither Viribus Wealth Management nor &Partners renders legal or tax advice. Please consult your tax or legal advisors before taking any action that may have tax consequences.
Why a generalist has a hard time with this
Every large employer builds a benefit package that belongs only to them. The plan documents run to hundreds of pages. The eligibility rules are specific. The deadlines are specific. And the way the pension, the Thrift Plan, the healthcare subsidy, the HSA and the Medicare transition interact with each other is specific.
A generalist advisor has to learn a new employer’s plan from scratch with every new client. That is not a realistic job. So in practice the advice stays general, and the client can be left to supply the specifics.
The specifics are where the consequences live. The subsidy accrual rule. The age-55 provision. The irrevocable 31-day enrollment window. The legacy Andeavor pension components. The Via Benefits transition at 65. None of these are exotic planning concepts. They are basic facts about a benefit package — and they do not appear in any textbook, any exam, or any advisor training program. You learn them by spending years inside the plan documents, and alongside the people living with the results.
That is the work this part of the practice is built to do.
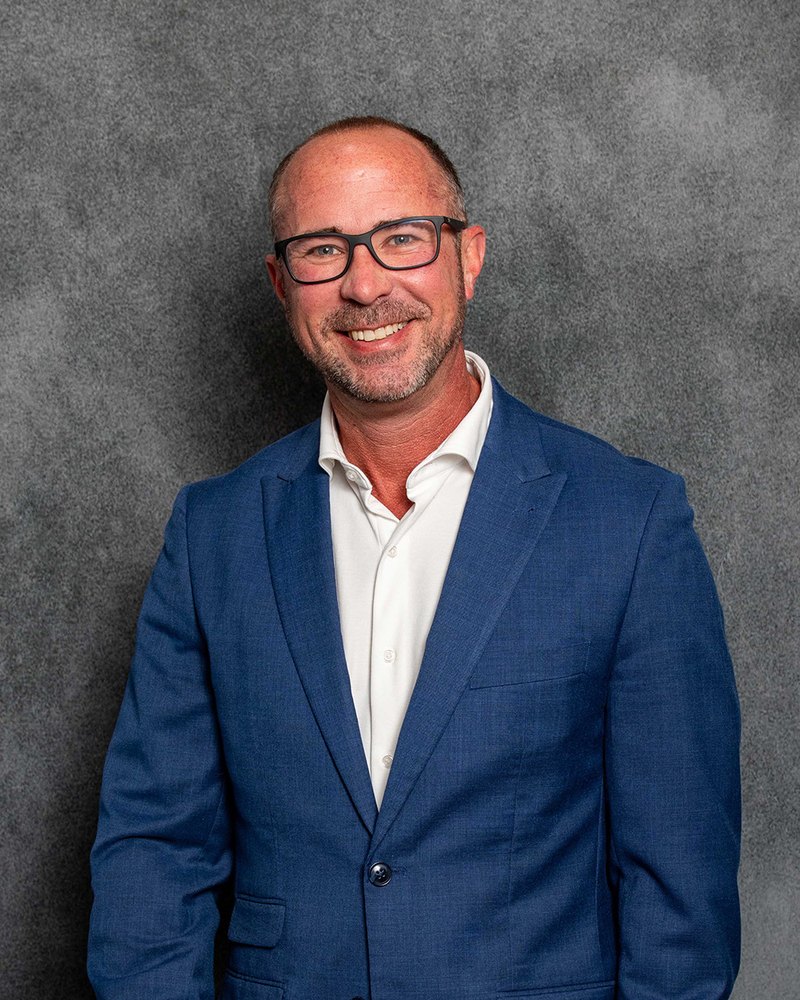
I grew up in Robinson.
That is the short version of why this practice looks the way it does. I know what the refinery means to that town, and I know that when someone at the plant is a year out from retiring, the conversation is already happening — in the break room, in the parking lot, at a kitchen table on a Sunday afternoon.
I have spent more than twenty years in financial services, and the work I have found most worth doing is the kind where the details are knowable and the stakes are concentrated into a handful of irreversible choices. That is exactly what retiring from Marathon looks like.
The office is in Terre Haute, about forty miles east. I am in Robinson regularly, and I would rather meet you there.
Reserve a seat
Retiring from the Robinson Refinery
Robinson, Illinois · 6:00 pm · Dinner provided
Seats limited
Pension vs. lump sum: running the numbers
Robinson, Illinois · 6:00 pm · Dinner provided
Seats limited
An hour, and no sales pitch
The plan mechanics
The pension election, the Thrift Plan, the 31-day healthcare window, and the age-55 provision, explained in plan language.
The sequence
Which decisions have to happen in what order, and which cannot be undone once the paperwork is signed.
Your questions
Time set aside for them. If a question needs your own numbers, we will say so rather than guess in the room.
RSVP
Tell us which date and how many seats. We will confirm by email.
"(Required)" indicates required fields
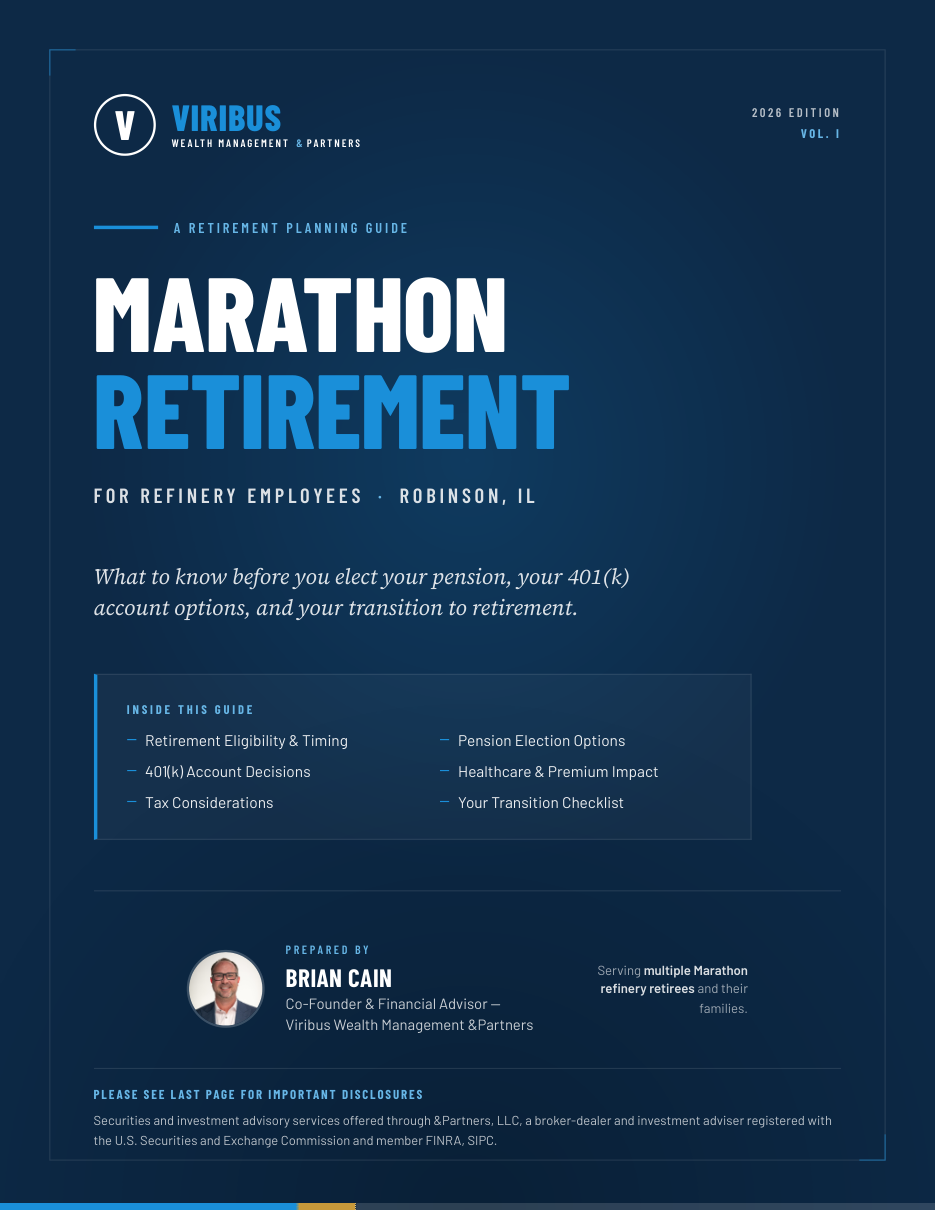
The Marathon Retirement Guide — 2026 Edition
A plain-English walkthrough of the retirement decisions specific to the Robinson Refinery: eligibility and timing, the pension, the Thrift Plan, healthcare before and after 65, the mistakes that come up most often, and a twelve-month countdown checklist with every phone number you will need.
Written independently, from the plan documents. Not produced by or affiliated with Marathon Petroleum.
Tell us where to send it.
"(Required)" indicates required fields
We will email you the guide and, if you’d like, occasional educational notes about retiring from Robinson. Unsubscribe any time. We do not sell or share your information.
The questions people actually ask
When can I retire from Marathon?
Eligibility for retirement under the MPC plans generally requires reaching age 50 with at least ten years of service and being vested. Meeting the minimum, though, is a different question from whether retiring at that point is a good idea: the healthcare subsidy you have earned, the pension calculation, and your bridge to Medicare all move depending on the date you pick. Confirm your own eligibility directly with the MPC Benefits Service Center.
Should I take my pension as monthly payments or as a lump sum?
There is no universal answer, and anyone who gives you one without looking at your situation is guessing. The comparison depends on your health and your spouse’s, the age difference between you, the interest rates in effect when you elect, how much of your retirement income is already guaranteed elsewhere, and what you want to leave behind. The election is not reversible, so it is worth modeling properly before the paperwork is signed.
What is the 4% healthcare subsidy accrual rule?
The subsidy MPC applies toward your retiree health premium is earned over time, accruing by year of service after age 30 until it reaches the full amount. If you retire before reaching the full percentage, the reduction applies for as long as you are on the plan. It does not catch up later. For people considering an early retirement date, this is often the single most consequential number in the decision, and it is the one most often overlooked.
What is the age-55 rule, and can rolling over my Thrift Plan cost me?
Most people know about the age-59½ threshold for retirement account withdrawals. Fewer know that if you separate from service in the calendar year you turn 55 or later, distributions from your workplace plan may be available without the early withdrawal penalty. Rolling that money into an IRA can remove that option. If you are retiring between 55 and 59½, the order in which you do things matters as much as what you do.
What happens to my health insurance between retiring and turning 65?
If you are eligible for the retiree health plan, you elect coverage during the 31-day window after you separate from service, and you choose between the plan options MPC offers for pre-65 retirees. That election is irrevocable outside of a qualifying event. One thing to know: employees hired on or after January 1, 2019 are not eligible for the retiree health plan, which changes the pre-65 planning problem substantially for that group.
I was hired after January 1, 2019. What’s different for me?
The main difference is retiree health coverage: that group is not eligible for the MPC Retiree Health Plan. That does not mean retiring early is off the table, but it does mean the bridge to Medicare has to be solved a different way, and the cost of that bridge becomes a central input into when you can realistically retire rather than an afterthought.
I came from Andeavor. Do I have two pensions?
Legacy Andeavor employees can have two separate pension components, one from the pre-2019 period and one after, which means two sets of election paperwork and two sets of choices, sometimes with different mechanics. It is worth confirming what you actually have well before your retirement date, because it is not unusual for one component to be overlooked entirely.
What happens when I turn 65?
At 65 you transition to Medicare, coordinated through Via Benefits, and your coverage and cost structure change again. Certain longer-tenured legacy employees receive an MPC subsidy toward that coverage. Medicare also introduces income-related premium surcharges, calculated from a tax return filed two years earlier, which means decisions you make at 63 can raise your premiums at 65.
Do I have to move my accounts to work with you?
No. A number of the conversations that start here are second opinions, and some of them end with us telling someone that what they already have in place is fine. If it makes sense to work together, we will say so. If it doesn’t, we will say that too.
Every plan detail on this page is described in general terms. Marathon Petroleum can amend or change its plans at any time. Always confirm your own numbers and eligibility directly with the MPC Benefits Service Center and your Summary Plan Description.
What actually happens if you reach out
01
A phone call.
Twenty minutes or so. You tell us where you are — a date in mind, a decision you’re stuck on, or just a general sense that you should probably be doing something. Nothing to prepare.
02
A review of what you have.
Your pension estimate, your Thrift Plan statement, your benefits summary. We go through the actual mechanics of your specific situation and show you what the choices in front of you really look like side by side.
03
You decide what happens next.
Some people take what they’ve learned and handle it themselves. Some want help executing it. Both are fine, and you will not be chased either way.
Start a conversation
Fill in the form, or call the office directly. If you are within a year of a retirement date, mention it — timing changes what we should look at first.
"(Required)" indicates required fields
Viribus Wealth Management &Partners
4600 South Springhill Junction Street
Terre Haute, IN 47802
Serving Robinson, Illinois and Crawford County — about forty miles west of our Terre Haute office.
Prefer to book directly?
Schedule a Retirement Readiness Review.
Securities and investment advisory services offered through &Partners, LLC, a broker-dealer and investment adviser registered with the U.S. Securities and Exchange Commission and member FINRA, SIPC. This content is for informational and educational purposes only and does not constitute investment, tax or legal advice. References to Marathon Petroleum, the Robinson Refinery, Andeavor, and related benefit plans are for identification purposes only. Viribus Wealth Management &Partners is not affiliated with or endorsed by Marathon Petroleum Corporation.
Plan details described on this page are general in nature and are believed to be accurate as of the date of publication. Marathon Petroleum may amend, terminate or change its plans at any time at its sole discretion. Always confirm current plan provisions and your individual eligibility directly with the MPC Benefits Service Center and your Summary Plan Description. Every situation is different — consult your own tax and legal advisors before making any retirement election.